Homeowners Insurance
What is scheduled personal property (jewelry, art)?
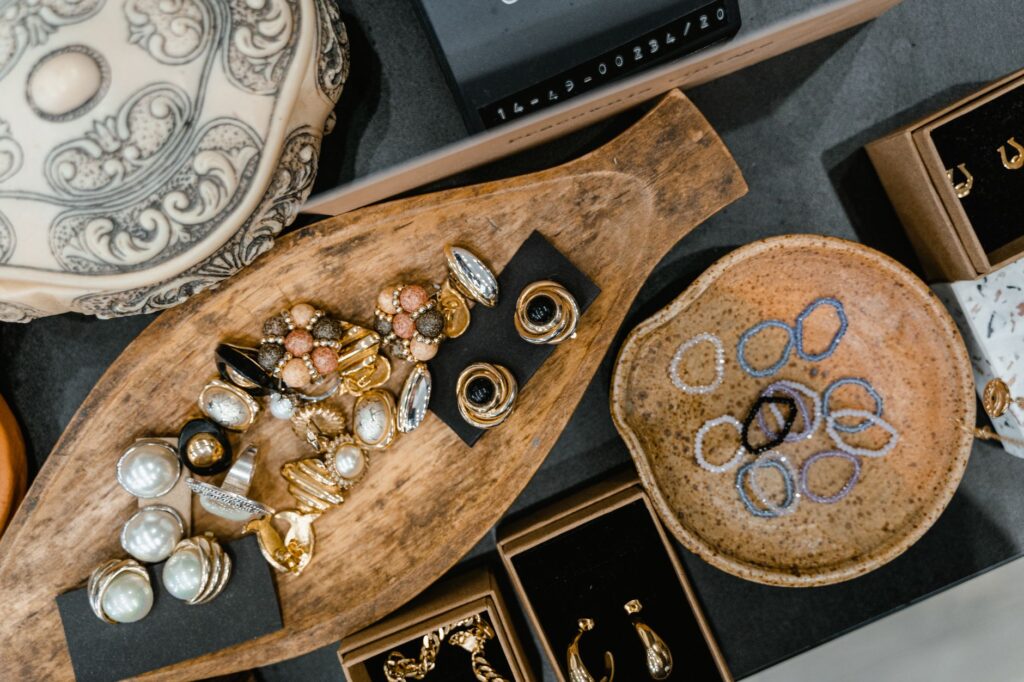
Many homeowners assume their standard insurance policy will fully replace valuable jewelry, fine art, or expensive collectibles after a disaster or burglary. In reality, standard policies enforce strict payout limits on valuable possessions, leaving significant financial gaps if an expensive item is lost or stolen. Understanding how scheduled personal property coverage works helps you decide if your most prized belongings need broader financial protection.
What is scheduled personal property coverage?
Scheduled personal property is an insurance endorsement or floater policy that provides dedicated coverage for individual, high-value belongings. When you schedule an item, your insurer lists that specific piece on your policy alongside its verified value.
A floater policy is an insurance add-on that provides specialized coverage for individual high-value items. Scheduling an item means listing and describing a specific valuable piece separately on your policy along with its appraised value.
Standard homeowners policies group your belongings together under general personal property coverage, but this general protection does not fully protect rare or expensive belongings. Scheduling individual items ensures that valuables like fine jewelry, artwork, furs, watches, and collectibles receive individualized protection. Instead of facing low theft caps, scheduled items receive the broadest protection possible under personal property floaters.
Related reading: Does homeowners insurance cover water damage from a burst pipe? · How much homeowners insurance do I need?
How does standard homeowners insurance limit jewelry and art?
A standard homeowners policy includes coverage for personal property, but it places special limits of liability on specific categories of high-value items. Most policies only pay a certain amount if jewelry, artwork, or electronics are stolen or damaged by covered disasters like fires or storms.
A limit of liability is the maximum dollar amount an insurance company will pay for a covered loss. Standard policies cover losses caused by specific perils, which are events or hazards that cause property damage. Covered perils include fire, windstorm, hailstorm, tornadoes, theft, and vandalism.
However, because jewelry is portable and can be easily stolen, standard policies enforce a relatively low limit of liability for theft. This theft limit is generally about $1,500. Under this restriction, an insurer will not pay more than the specific amount stated in the policy for any single piece of jewelry or valuable item. If an expensive engagement ring, antique watch, or rare painting is stolen, the standard policy payout may leave you with substantial out-of-pocket costs.
What are the ways to increase coverage for your valuables?
If you own expensive jewelry, furs, collectibles, art, or electronics that would be difficult to replace, you can choose between two main methods to increase your coverage. You can either raise the liability limits on your existing policy or purchase a floater policy to schedule individual items.
Raising your limit of liability is the less expensive option of the two. While this approach increases your coverage ceiling, the payout amounts remain strictly limited for both individual pieces and overall losses. For example, your policy might set a limit of $2,000 for the loss of an individual piece, with an overall loss limit of $5,000 for the entire claim. This option may work well for modest collections, but it may not provide enough coverage for higher-priced items.
Purchasing a floater policy to schedule your individual valuables is the more costly option, but it provides the broadest protection. By scheduling individual items, you insure each piece for its specific worth rather than subjecting it to blanket category caps. Before you can purchase a floater policy, your insurer will require that the covered items receive a professional appraisal. You can ask your insurance professional to recommend a reputable appraisal firm to determine the accurate replacement value of your items.
| Coverage Feature | Raising Liability Limits | Scheduling Items with a Floater |
|---|---|---|
| Relative Cost | Less expensive option | More costly option |
| Scope of Protection | Limited protection under standard policy terms | Broadest protection available for valuables |
| Loss Limits | Capped per piece (such as $2,000) and overall (such as $5,000) | Covers the specific appraised value of each scheduled piece |
| Appraisal Requirement | Generally not required for blanket limit increases | Items must be professionally appraised before purchase |
| Accidental Loss Coverage | Excludes accidental losses like misplaced items | Covers accidental losses, such as dropping jewelry down a drain |
What types of losses do scheduled floaters cover?
A floater policy covers losses of any type, providing protection for incidents that standard homeowners policies specifically exclude. Most notably, floaters protect against accidental losses that happen during everyday use.
Standard policies only respond to named perils like fires, storms, or vandalism, and they enforce strict restrictions on theft. In contrast, scheduled floater policies cover unique mishaps, such as accidentally dropping an expensive ring down the kitchen sink drain. They also cover situations where you accidentally misplace an item away from your house, such as leaving an expensive watch in a hotel room.
Understanding what standard policies exclude highlights why scheduled coverage is valuable. Standard home policies do not cover wear and tear, meaning companies will not pay for damages that happen over time, like rotted boards or cracking window seals. Basic policies also do not cover rodent or insect damage, floods, earthquakes, or fallen trees in your yard unless storm damage damages your house or blocks your driveway. Floater policies step in to bridge major protection gaps by covering unexpected, accidental mishaps involving your most prized possessions.
How do you set up scheduled personal property coverage?
Setting up scheduled personal property coverage requires documenting your belongings, obtaining an appraisal, and coordinating with your insurer to adjust your policy. Taking structured steps ensures your items are properly valued and fully protected against potential losses.
Follow these steps to establish scheduled coverage for your valuable items:
- Take a comprehensive home inventory: Use a home inventory checklist to create a detailed record of what you own. Documenting your personal property ensures you have enough coverage to replace your belongings if they are destroyed by fire, tornadoes, hailstorms, or theft.
- Get items professionally appraised: Before you can schedule an item on a floater, the piece must be professionally appraised to verify its exact worth. You can ask your insurance agent or professional to recommend a reputable appraisal firm in your area.
- Review policy terms and replacement costs: Check whether your underlying homeowners policy is a replacement cost policy, which mortgage lenders frequently require as a loan condition. A replacement cost policy is an insurance policy that pays the actual cost to repair or replace property at current prices.
- Choose your deductible carefully: A deductible is the amount you have to pay before the insurance company will pay a claim. Selecting a higher deductible will lower your premium, while a lower deductible means paying less out of pocket when filing a claim.
- Ask about available discounts: You can often lower the overall cost of your insurance by asking your company about discount programs. Many insurers offer premium discounts for installing a home security alarm, having a fire sprinkler system, bundling other policies with the same company, or remaining claim-free for the past three years.
What should you check when shopping for extra coverage?
Shopping for coverage on valuables requires comparing policy terms, checking company credentials, and avoiding dangerous gaps in your protection. You should always obtain quotes and verify that your insurer is properly licensed before purchasing coverage.
You can use price quotes to compare policies and find the option that best fits your pocketbook and coverage needs. When shopping, contact your state insurance department or call their consumer help line, such as the Texas Department of Insurance Help Line at 800-252-3439, to verify that the company or agent you are considering holds an active license.
It is critical to avoid coverage gaps during this process. Never cancel an existing policy until you receive your new policy or a written statement of coverage from the insurer. If you experience trouble finding an insurer willing to sell you coverage, you can explore specialized state assistance programs, such as the Texas FAIR Plan at 800-979-6440.
Key takeaways
- Standard homeowners policies cap theft coverage for jewelry at relatively low amounts, generally around $1,500.
- Scheduling personal property through a floater policy provides the broadest protection and covers losses of any type, including accidental loss.
- Valuable items like jewelry, furs, art, and collectibles must be professionally appraised before an insurer will issue a floater policy.
- Raising your liability limit is a cheaper way to increase coverage, but payout amounts remain capped per piece and per claim.
- You can manage premium costs by adjusting your deductible and qualifying for discounts like home security alarms or fire sprinklers.
Common mistakes to avoid
- Assuming standard policies cover full value: Believing standard homeowners insurance will replace expensive jewelry, art, or electronics leaves you exposed to low liability caps, such as the typical $1,500 theft limit.
- Skipping a professional appraisal: Failing to obtain a professional appraisal prevents you from scheduling items on a floater policy and leaves their true replacement value unverified.
- Neglecting accidental loss risks: Forgetting that standard policies exclude accidental losses—like leaving a watch in a hotel room or losing a ring in a sink drain—leaves you without coverage for common accidents.
- Creating coverage gaps during transitions: Canceling an old policy before receiving your new policy or written statement of coverage leaves your valuable property completely unprotected.
Frequently asked questions
Does homeowners insurance cover dropping a ring down the drain?
A standard homeowners insurance policy does not cover accidental losses like dropping a ring down the kitchen sink drain. To protect against accidental losses of any type, you must purchase a floater policy and schedule the ring individually.
Why do standard insurance policies have low theft limits for jewelry?
Standard policies place a relatively low limit of liability on jewelry theft, generally around $1,500, to keep coverage affordable for policyholders. Because jewelry is small, valuable, and easily stolen, insurers restrict standard theft payouts unless you buy extra coverage.
Can artwork and electronics be scheduled on an insurance policy?
Most standard policies only pay a limited amount if artwork or electronics are stolen or damaged by fires or storms. You can purchase extra coverage to protect expensive art, collectibles, electronics, and jewelry against broader risks.
How do security alarms affect the cost of insuring valuables?
Installing a home security alarm can qualify you for premium discounts from most insurance companies. Insurers also offer discounts for having a fire sprinkler system, bundling multiple policies, or remaining claim-free for the past three years.