Auto Insurance
How much does adding a teen driver to my policy cost?
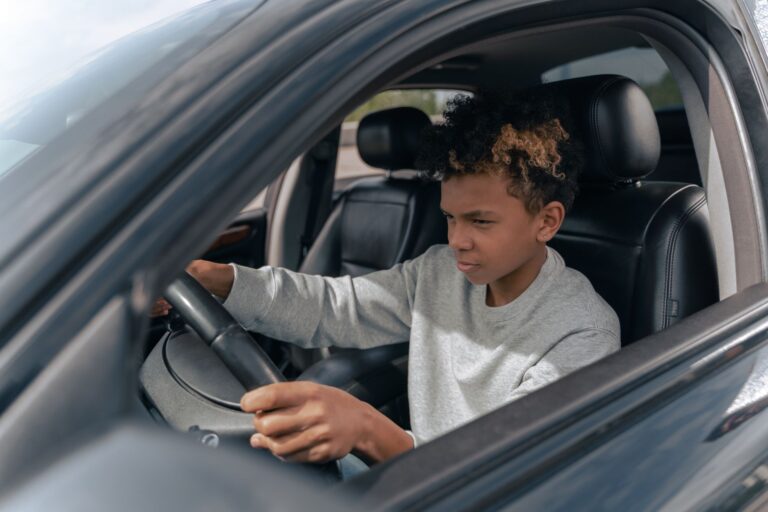
Bringing a newly licensed driver into your household is an exciting milestone, but it quickly introduces changes to your monthly household budget. Because young motorists have minimal behind-the-wheel experience, insurance companies adjust their rates to match that heightened risk. Understanding how insurers calculate these rate increases helps you anticipate the change and identify practical ways to keep your family coverage affordable.
Why does adding a teen driver to your policy cost so much?
Insuring a new teen driver is expensive because teenagers carry the highest crash risk of any age category. Having very little driving experience makes them more vulnerable to accidents, which prompts insurers to raise policy rates to offset potential losses.
Mature drivers generally experience far fewer wrecks than younger operators. Because of this historical data, insurance providers routinely charge higher premiums whenever teenagers or young people under age 25 drive a vehicle on the policy. When you add your teen, your policy takes on this elevated statistical risk, which often leads to significant premium increases.
Liability insurance—coverage that pays for damages to another person or property—is mandatory for all motorists in states like Washington. Because inexperienced drivers present a greater risk of causing damage, maintaining adequate liability limits on a policy with a teen driver inevitably raises your overall cost.
Related reading: How much does adding a teen driver to my policy cost? · How much does car insurance cost per month for a new driver?
What factors determine how much adding a teen driver to my policy will cost?
Insurance companies do not use a single flat pricing model when adding a driver. Instead, the final price depends on a combination of personal, regional, and policy-specific factors that reflect your household’s overall risk profile.
The primary elements insurers evaluate when calculating your rate include:
- Driver age and gender: Insurers charge more for drivers under 25, especially teenagers. Statistically, female drivers tend to have fewer accidents, fewer driving-under-the-influence violations (DUIs), and less severe wrecks than male drivers, meaning young women often pay less than young men.
- Driving records: A clean driving history results in a lower premium. Serious moving violations or accidents increase costs, and new drivers without an established insurance track record routinely face higher baseline rates.
- Vehicle usage and mileage: Driving more miles creates a greater likelihood of a collision. Using a car for daily commuting or work costs more to cover than occasional “pleasure use.”
- Location and vehicle storage: Urban areas experience higher rates of accidents, vandalism, and theft, resulting in higher premiums than small towns or rural areas. Parking your car on the street rather than in a secure garage also increases rates.
- Regional cost trends: Premiums vary between regions and states based on local weather trends, the frequency and cost of litigation, car repair costs, medical care prices, and the prevalence of insurance fraud.
- Credit-based insurance score: Similar to a credit score, a credit-based insurance score is a statistical tool that predicts the likelihood of you filing a claim and the likely cost of that claim.
- Coverage types and deductibles: Your deductible is the amount you pay out of pocket before your insurance applies to a claim. Selecting higher liability limits or adding optional protections like collision insurance raises your premium, whereas choosing a higher deductible lowers it.
Insurance companies evaluate these factors collectively to establish your rate. By law, insurers can never use race or religion to set your insurance prices.
How does your vehicle choice affect your teen driver costs?
The type of car your teen drives directly impacts the price of your policy. The purchase cost of the car, its repair costs, engine size, theft likelihood, and overall safety record all factor into your insurance premium.
Inexpensive vehicles or those with high safety ratings usually cost less to insure. Vehicles equipped with high-quality safety equipment can also qualify for special premium discounts. However, purchasing an older, cheaper car does not automatically guarantee lower premiums or superior safety. Before buying any car for a young driver, you should request an insurance quote to verify the actual coverage price.
Insurers also evaluate the physical damage a vehicle could inflict on other vehicles during an accident. If a particular car model carries a higher risk of causing extensive damage to others, the insurer may charge more for mandatory liability coverage.
If you choose an inexpensive vehicle, you might consider adjusting your physical damage coverages to lower costs:
- Collision insurance: Collision insurance covers only wrecks. It pays for damage to your car if it collides with another vehicle or object.
- Comprehensive insurance: Comprehensive insurance covers non-collision losses, including theft and hail damage. If your teen drives an older car with limited cash value, skipping comprehensive coverage while maintaining collision protection can help reduce your total premium.
Is it cheaper to add a teen to your policy or buy a separate policy?
With only a few exceptions, it is generally easier and far less expensive to add your teen to your existing auto policy than to buy a separate policy. Grouping vehicles and drivers under one household policy typically keeps rates more manageable than establishing standalone coverage for an inexperienced driver.
However, specific circumstances may require or favor a standalone policy for a young driver. Review the side-by-side comparison below to see how these two options function.
| Policy Option | Relative Cost | Best Suited For | Key Requirements and Limitations |
|---|---|---|---|
| Adding Teen to Existing Policy | Usually cheaper | Teens living at home sharing family vehicles | Teen must reside in your household; all household vehicles are covered under one policy structure. |
| Buying a Separate Policy | Usually more expensive | Independent teens or households with unique risk profiles | Required if the vehicle is titled and registered only in the teen’s name, or if the teen moves out permanently. |
A separate policy may also make sense if your family’s current premiums are already elevated due to other high-risk drivers on the policy. If you are navigating this choice, consult an insurance agent to compare side-by-side quotes for both arrangements.
How do custody arrangements affect teen driver insurance?
When parents are divorced or separated and a teen splits time between two homes, insurance arrangements can become complicated. Insurers enforce different requirements depending on where the vehicle is kept and how often the teen drives.
Some insurance companies require teen drivers to appear on both parents’ auto policies if the teen operates vehicles at both residences. Other insurers only require proof of insurance at the home where the teen lives for the majority of the time, allowing you to avoid paying for coverage on two separate policies.
Because requirements differ significantly across carriers, both parents should consult their respective insurance agents to ensure coverage rules are properly met before the teen begins driving between households.
When should you notify your insurer about a teen driver?
You should contact your insurance company or agent several months before your teen begins driving or obtains a learner’s permit. Taking action early allows you to review your coverage limits, prepare for premium adjustments, and shop around for competitive rates.
Drivers with a learner’s permit are handled differently than fully licensed drivers. While you are not legally required to purchase insurance for a teen with a learner’s permit, you must always notify your insurance provider that a student driver is learning in your car. Many insurers mandate notification whenever a household member’s driving status changes.
Failing to disclose a student or licensed driver living in your home carries serious consequences. If an unlisted driver has an accident in your vehicle, the insurance company could deny your claim, void your policy, or refuse to renew your coverage.
How can you lower the cost of adding a teen driver?
Although adding a teen driver to your policy increases your overall bill, several proven strategies can help you secure discounts and reduce your rates:
- Good student discounts: Teens who maintain good grades or high test scores can earn discounts that sometimes last for years.
- Driver training courses: Teens who complete an approved driver’s education course usually receive an auto insurance discount.
- Telematics and usage-based programs: Enrolling in a telematics app or installing a vehicle monitoring device tracks your teen’s driving habits. If they demonstrate safe driving practices, the insurer will usually award a discount.
- Adjusting deductibles: Increasing your comprehensive and collision deductibles lowers your recurring premium payments.
- Policy bundling: Inquire with your agent about multi-policy bundling discounts to reduce overall coverage costs.
- Student away at college: If your teen attends college without a vehicle and the family cars stay at home, you may qualify for an additional discount. If your teen takes a car to an out-of-state college, your policy stays intact unless the vehicle is registered in that state.
- Comparison shopping: Before making a major policy change, obtain quotes from multiple licensed carriers. Comparing complaint data on customer service and claims handling trends helps you identify reliable insurers with competitive pricing.
Key takeaways
- Adding a teen driver to an existing household policy is expensive due to their high crash risk, but it is usually cheaper than purchasing a separate policy.
- Your rate increase is determined by driver age, gender, driving records, vehicle choice, location, credit-based insurance scores, and policy deductibles.
- Always notify your insurance company when your teen receives a learner’s permit to prevent claim denials or policy cancellations.
- You can offset rate increases through good student discounts, driver education courses, telematics tracking apps, higher deductibles, and vehicle selection.
Common mistakes to avoid
- Hiding a permit driver from your insurer: Failing to report a teen who is learning to drive can cause the insurer to deny accident claims, void the policy, or decline renewal.
- Buying a car before checking insurance rates: Assuming an older or cheaper car is cheap to insure is a mistake; always get insurance quotes on the specific make and model prior to purchase.
- Missing out on academic and training discounts: Forgetting to submit proof of driver education completion or good grades leaves valuable multi-year discounts on the table.
- Overlooking policy limits: Adding a high-risk driver without reviewing your liability limits can leave your household exposed if a major accident occurs.
Frequently asked questions
Does my teen need insurance with a learner’s permit?
You are not legally required to buy insurance for a teen with a learner’s permit. However, many insurers require you to report student drivers, and failing to inform your insurer can lead to denied claims or policy cancellation if an accident occurs.
Can my teen stay on my policy if they take a car to college?
Yes, you do not need to change your policy if your teen takes a car to college out of state, unless you register the car in that state. If your teen attends college without a vehicle and the cars remain at home, you may even qualify for a discount.
Which parent insures a teen driver after a divorce?
Requirements vary by insurance company. Some insurers require the teen to be listed on both parents’ policies if they drive at both homes, while others only require proof of insurance at the home where the teen lives for the majority of the time.
Do male and female teen drivers cost the same to insure?
No, gender affects auto insurance costs. Statistically, women are involved in fewer crashes, fewer DUIs, and less severe accidents than men, which means women often pay lower insurance rates than their male counterparts.